Offer, reject in writing
Alabama coverage menu: liability required, uninsured motorist on the policy unless rejected
Alabama asks for liability and puts uninsured motorist coverage on every policy unless the named insured turns it down. There is no PIP. Here is what each line pays and where the gaps sit.
By CoverOath Editorial Team Updated 5 min read
The promise, in short
Alabama requires 25/50/25 liability: $25,000 per injured person, $50,000 per crash and $25,000 for property damage. State law also puts uninsured motorist coverage at those bodily injury limits into every auto liability policy, and in Alabama it also answers when the at-fault driver's limits are too low. The named insured may reject it. Alabama has no personal injury protection. The Alabama Department of Insurance takes consumer calls at 1-800-433-3966.
- Minimum liability
- 25/50/25
- PIP and MedPay
- No PIP; MedPay optional
- UM/UIM
- Included; may be rejected
Alabama coverage menu
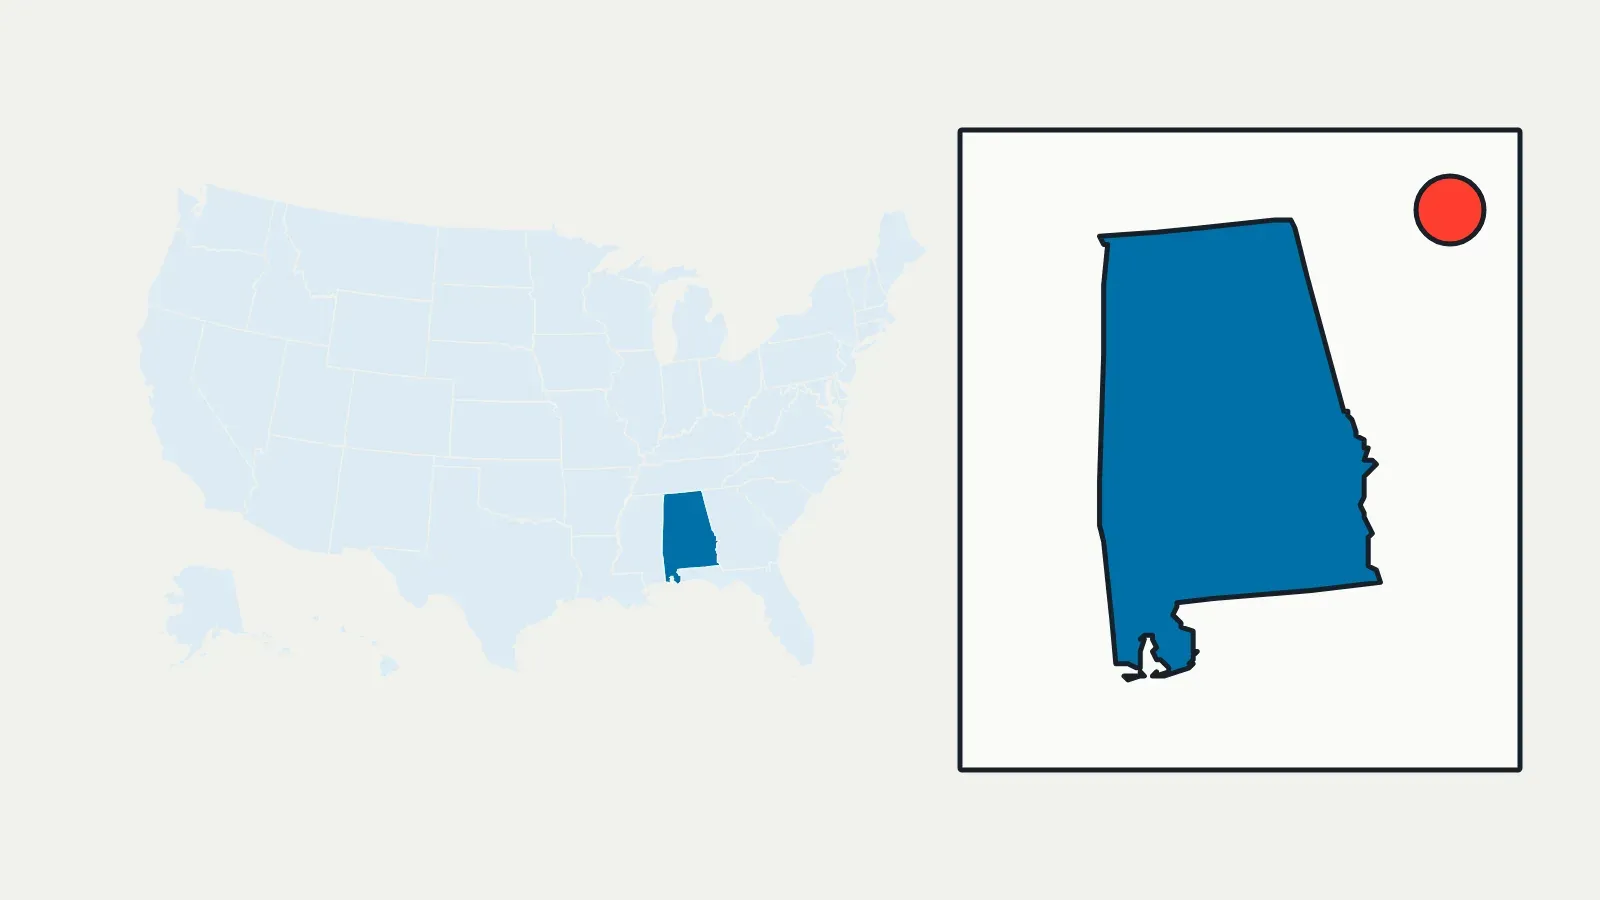
What an Alabama policy must carry
Alabama is a fault (tort) state. The coverage you must buy is liability, which pays the people you injure and the property you damage when a crash is your fault. It does not pay for your own injuries or your own car.
| Coverage | Minimum | What it pays |
|---|---|---|
| Bodily injury, per person | $25,000 | One injured person's claim |
| Bodily injury, per accident | $50,000 | Everyone injured in one crash |
| Property damage, per accident | $25,000 | Other people's cars and property |
Those numbers are a floor, not a target. A crash with two badly hurt people or a damaged late-model car can pass them, and whatever a court awards above your limits is owed by you. The liability limits guide walks through how people pick higher limits.
Uninsured motorist coverage comes on the policy
Under Code of Alabama §32-7-23, an auto liability policy issued for a vehicle registered or principally garaged in Alabama must include uninsured motorist coverage at no less than the minimum bodily injury limits, $25,000 per person and $50,000 per accident. It pays you and the people insured under your policy for injuries caused by a driver who should pay but cannot.
Who counts as uninsured
The statute lists a driver with no bodily injury liability insurance, one insured below the state minimum, and one whose insurer becomes insolvent after the policy is issued.
Underinsured is built in
The same definition covers a driver whose liability limits are less than the damages you are legally entitled to recover. Alabama does not sell UIM as a separate line.
The named insured has the right to reject the coverage. Once it is rejected, the insurer does not have to add it back on a renewal unless a named insured asks for it in writing. The statute does not spell out the form of the first rejection, so if you are not sure what was signed, ask the insurer for the document on file.
No PIP; medical payments is optional
Alabama has no no-fault system and no personal injury protection requirement; the Alabama Department of Insurance lists it among the tort states. Injuries are paid by the at-fault driver's liability insurance, by your UM coverage when that driver has too little, or by your own health plan.
Medical payments coverage is an optional add to the policy. It pays medical bills for you and your passengers up to a small limit, whoever caused the crash, and it does not replace lost income.
UM limits, property damage and stacking
- Bodily injury only. Section 32-7-23 covers bodily injury, sickness, disease and death. It does not require uninsured motorist property damage; damage to your car from an uninsured driver goes through collision, if you carry it.
- Higher limits. The statute sets only the 25/50 floor. You can ask your insurer for UM limits above it, for example to match your liability limits.
- Stacking within one policy. Recovery under one policy is limited to the primary coverage plus the coverage for additional vehicles, but not more than two additional coverages. A three-car policy with $25,000 UM per car can reach $75,000 for one injured person. See how stacking works.
The statute caps what one policy can stack; it does not say how several separate policies combine. That depends on the policy wording and court decisions, so read the limit of liability and other insurance sections of each policy.
Optional coverages Alabama drivers add
- Collision and comprehensive for your own car. A lender or lease company will require both. See collision coverage.
- Rental reimbursement and roadside help, sold as add-ons. See rental reimbursement.
- Gap coverage on a financed car whose loan is larger than its value. See gap insurance.
Where to check and complain
- Read your declarations page for your liability limits and whether uninsured motorist coverage is listed, and at what limit.
- Ask the insurer for a copy of any UM rejection on file if the coverage is missing.
- Call the Alabama Department of Insurance Consumer Services at 1-800-433-3966 or 334-241-4141 if an insurer will not explain a coverage or a claim decision.
Questions drivers ask
Is uninsured motorist coverage required in Alabama?
It must be included in every Alabama auto liability policy at the 25/50 bodily injury minimum, but the named insured may reject it. If you did not reject it, it is on your policy.
Does Alabama have underinsured motorist coverage?
Yes, inside the uninsured motorist coverage. Alabama's statute treats a driver whose liability limits are below your damages as uninsured, so one coverage answers both cases.
Can I stack uninsured motorist coverage in Alabama?
Within one policy, the statute allows the primary coverage plus the coverage of up to two additional vehicles. How separate policies combine depends on their wording. See stacking.
Is PIP required in Alabama?
No. Alabama is a tort state with no PIP requirement. Medical payments coverage is optional.
Drawn from
- Alabama Department of Insurance — Auto insurance FAQ (25/50/25)
- Alabama Department of Insurance — State auto insurance laws (tort and no-fault states)
- Code of Alabama §32-7-23, uninsured motorist coverage (Justia, 2009 edition)
- Alabama Department of Insurance — Contact us
Facts on this page were checked against these sources on November 15, 2026. The text of §32-7-23 was read in the 2009 Justia edition, whose history line ends with a 1984 act; confirm the current wording in the official Code of Alabama.
Have this coverage priced
CoverOath doesn't sell insurance. Answer five questions and CoverOath passes your request to licensed insurance agents and insurers, who can quote the coverage; you decide whether to buy anything.
- 1 The coverage you want priced.
- 2 Where an agent can reach you, and your consent.
- 3 A licensed insurance agent or insurer contacts you with a quote. Nothing is bought until you agree.
CoverOath is not paid by you. The licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Adjacent layers
-
Core coverage
Uninsured motorist coverage (UM)
Pays your injuries when an uninsured or hit-and-run driver is at fault. Required in about 20 jurisdictions.
-
Fine print
Stacking UM/UIM coverage
Whether UM limits on several cars add up. Pennsylvania and Florida stack by default; California bans it.
-
Core coverage
Medical payments coverage (MedPay)
Pays crash medical and funeral costs for you and passengers, whoever was at fault. Required in Maine and New Hampshire.